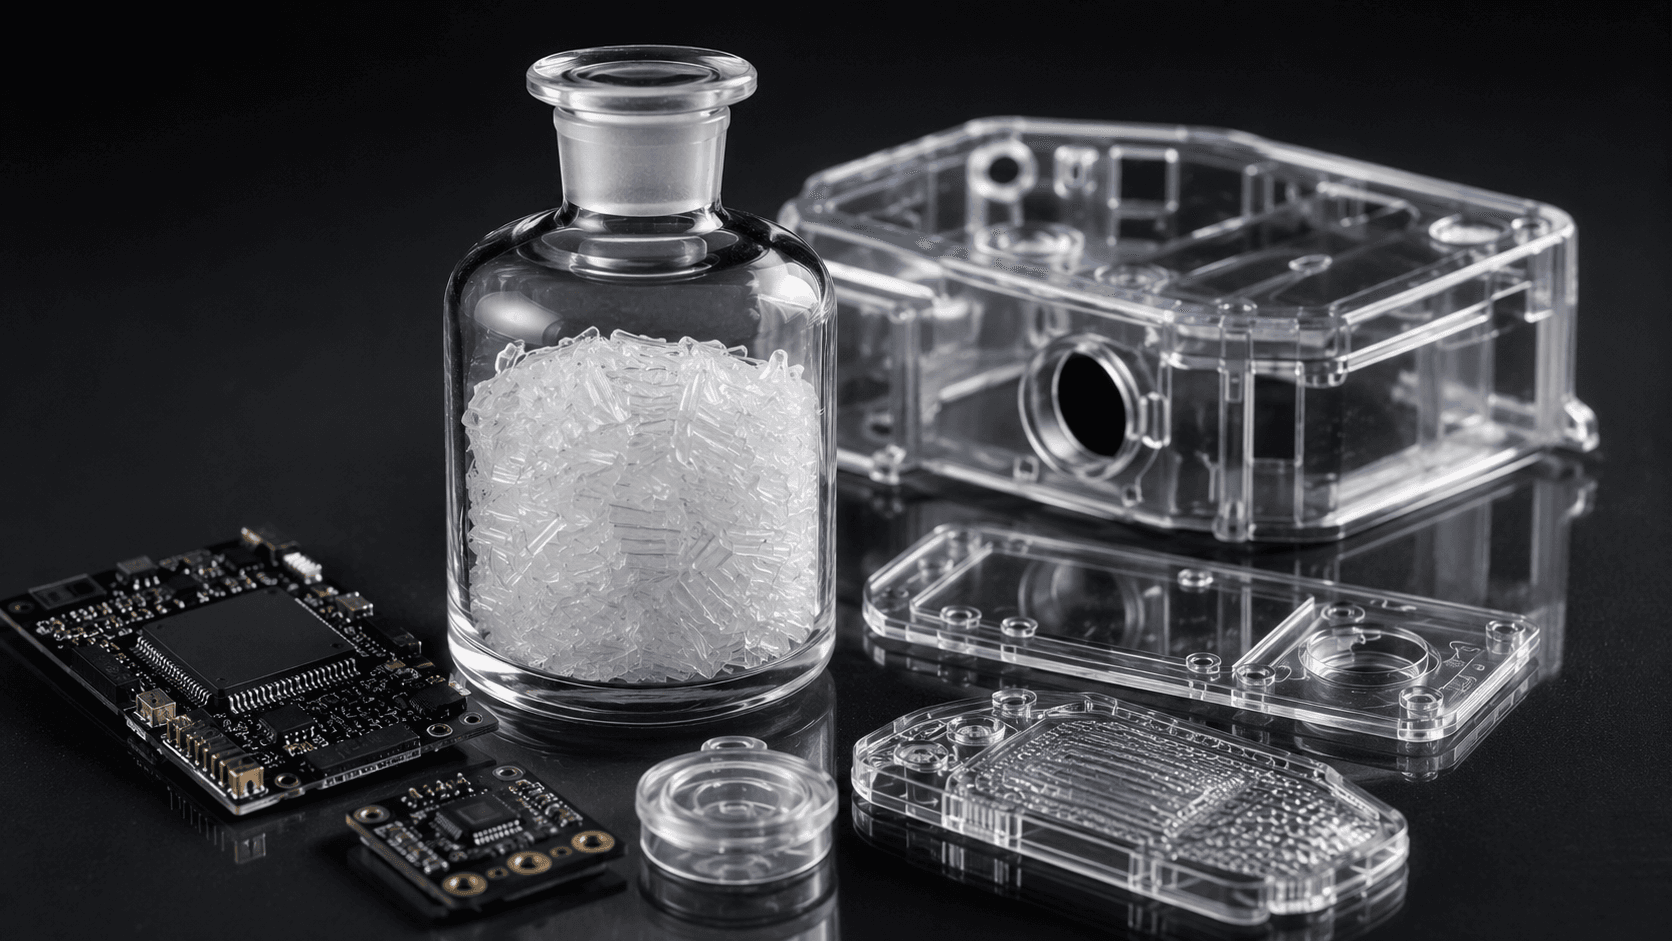
Few industrial chemicals occupy such a unique position between commercial necessity and regulatory controversy as Bisphenol A (BPA). For decades, BPA has served as one of the most important building blocks in modern manufacturing, enabling the production of polycarbonate plastics and epoxy resins used across countless industries.
At the same time, growing concerns regarding potential endocrine-disrupting effects have made BPA one of the most scrutinized chemicals globally. Regulatory agencies continue to impose restrictions in certain consumer applications, particularly food-contact materials, while industrial demand remains remarkably resilient.
The result is a market that continues to grow despite increasing regulatory pressure.
Why BPA Remains So Important
Bisphenol A is primarily used in the production of:
Polycarbonate plastics.
Epoxy resins.
Electronic components.
Automotive materials.
Construction products.
Industrial coatings.
Its popularity stems from the performance characteristics it provides.
Polycarbonate materials derived from BPA offer:
High impact resistance.
Optical clarity.
Heat resistance.
Electrical insulation properties.
Meanwhile, BPA-based epoxy resins deliver:
Chemical resistance.
Adhesion performance.
Corrosion protection.
Long-term durability.
These properties explain why BPA remains difficult to replace in many industrial applications.
The Electronics Industry Continues to Drive Demand
The most important growth engine for BPA today is electronics manufacturing.
Polycarbonate plastics and epoxy systems are widely used in:
Consumer electronics.
Data center infrastructure.
Electrical connectors.
Circuit boards.
Telecommunications equipment.
Advanced industrial electronics.
As digitalization, artificial intelligence and electrification continue expanding globally, demand for high-performance engineering materials remains strong.
This is one reason analysts expect the BPA market to continue growing despite regulatory headwinds.
Regulatory Pressure Continues to Increase
The BPA market cannot be discussed without addressing regulation.
Over the past decade, multiple jurisdictions have introduced restrictions on BPA use in specific consumer applications.
Areas of concern include:
Food-contact materials.
Infant products.
Beverage containers.
Consumer packaging.
Regulatory developments have occurred across:
The European Union.
Canada.
Multiple US states.
Other developed markets.
The European Union has also expanded scrutiny through its regulatory framework for substances of very high concern (SVHC) under REACH.
However, these restrictions are largely concentrated in sensitive consumer-facing applications rather than industrial manufacturing uses.

Why BPA-Free Alternatives Have Not Fully Replaced BPA
Although significant research has focused on alternative materials, widespread substitution remains challenging.
Manufacturers continue to face several obstacles:
Higher alternative material costs.
Performance limitations.
Supply chain constraints.
Qualification requirements.
Long product approval cycles.
For electronics and industrial applications in particular, BPA-based materials often provide performance characteristics that are difficult to replicate economically at scale.
As a result, many industries continue to rely heavily on BPA despite growing regulatory scrutiny.
The Market Is Still Growing
Despite ongoing controversy, BPA remains a large and expanding market.
Industry estimates place the BPA market at approximately USD 22.4 billion in 2025, with forecasts suggesting growth to nearly USD 34.8 billion by 2034.
Several factors support this outlook:
Rising electronics demand.
Growth in engineering plastics.
Expansion of electrical infrastructure.
Increased industrial manufacturing.
Demand for durable epoxy systems.
These drivers continue to offset demand losses in restricted consumer applications.
China Is Expanding Capacity Aggressively
China remains one of the most important markets for BPA production and consumption.
The country's growing electronics, automotive and industrial sectors continue to require substantial volumes of polycarbonate and epoxy resin feedstocks.
A major development in 2026 involves the joint venture between Wanhua Chemical and Pingmei Shenma Group to build approximately 370,000 tonnes per year of BPA capacity.
The project represents one of the most significant BPA-related investments announced during 2026 and highlights continued confidence in long-term demand growth.
For industry participants, the project also reinforces China's ambition to strengthen domestic materials supply chains and reduce dependence on imports.
Polycarbonate Growth Remains the Key Story
While BPA serves multiple industries, polycarbonate production remains the most strategically important downstream market.
Polycarbonate demand is being supported by:
Electric vehicles.
Consumer electronics.
Renewable energy infrastructure.
Medical devices.
Industrial automation.
As these sectors continue expanding, BPA consumption is expected to remain closely tied to broader technology and industrial investment trends.
What Buyers Should Watch Through 2030
Procurement teams and industry participants should closely monitor:
REACH regulatory developments.
BPA restriction proposals.
Polycarbonate demand growth.
Chinese capacity additions.
Electronics manufacturing trends.
Availability of BPA alternatives.
The interaction between regulation and industrial demand will continue to define market direction.
The Bottom Line
Bisphenol A remains one of the chemical industry's most important and debated materials. Regulatory scrutiny continues to intensify, particularly in food-contact and consumer applications, yet industrial demand remains robust due to BPA's critical role in polycarbonate plastics and epoxy resins.
The combination of strong electronics demand, ongoing polycarbonate growth and major investments such as the new Wanhua-Pingmei Shenma project suggests that BPA will remain strategically important for years to come. While alternative materials continue to emerge, few can currently match BPA's combination of performance, availability and cost efficiency at industrial scale.
For buyers, manufacturers and investors alike, BPA remains a chemical worth watching closely.
Interested in sourcing BPA, polycarbonate feedstocks or specialty resin intermediates? Explore verified suppliers and market opportunities on our platform today.
Biotin CAS: 58-85-5