 In 2023, analysts predict that China will import a record amount of crude oil due to rising gasoline consumption as more people travel as a result of the removal of COVID-19 regulations and the startup of new refineries.
The issue is cited from Reuters in early 2023. China's crude imports may rise by 500,000 to 1 million barrels per day (bpd) or more this year, reaching as high as 11.8 million bpd, experts from four industry consultancies, including Wood Mackenzie, FGE, Energy Aspects, and S&P Global Commodity Insight, say, this would reverse a decline from the previous two years, and breaking the previous record of 10.8 million bpd set in 2020. The four consultancies predicted that Chinese refineries will boost oil throughput by 850,000 Due to growing local demand and appealing export markets, production is expected to climb to 1.2 million bpd over 2022 levels, or 6% to 9%.
Another positive development for the oil market will be the expectation of robust demand from the largest importer in the world, which will add to the support already provided by the OPEC+ producing group's output cutbacks and western sanctions against Russian shipments.
China has seen an increase in demand for gasoline and jet fuel when COVID limits were removed in December. Sun Jianan, an analyst at Energy Aspects, predicted that gasoline and jet fuel would be the main drivers of the increase in demand for liquid fuels. By the end of 2023, Sun predicted that jet fuel usage would be 90% higher than it was before COVID.
As per FGE analyst Mia Geng and Energy Aspects' Sun, the rebound in China's manufacturing and real estate sectors will take longer to manifest, which will slow down demand growth for diesel, a crucial industrial and transportation fuel, and naphtha, a petrochemical feedstock.
Refiners will be encouraged to increase runs in order to maintain profitable export cargoes and deliver more feedstocks to the petrochemical industry, analysts said, in addition to meeting the growing domestic demand.
Industry sources predict that two new PetroChina-owned refineries, Guangdong Petrochemical and Jiangsu Shenghong Petrochemical, with a combined capacity of 520,000 bpd, would begin functioning commercially in the coming months.
According to a corporate source, a third greenfield refinery, the 400,000 bpd Shandong Yulong Petrochemical facility, may start importing crude towards the end of 2023 in preparation for potential test runs.
Experts did list several reasons to be wary of demand projections despite all the favorable elements. External hindrances, such as a bleak outlook for the world economy, would put stress on China's export industry. The potential for a COVID virus return and the uncertainty surrounding China's fuel export policy were listed as additional risks by analysts.
References:
Aizhu, Chen & Xu, Muyu. 2022. China set for record crude oil imports in 2023, analysts say. Reuters.
Photo by evening_tao via https://www.freepik.com/
China is On Track to Achieve Significant Increase in Crude Oil Imports in 2023
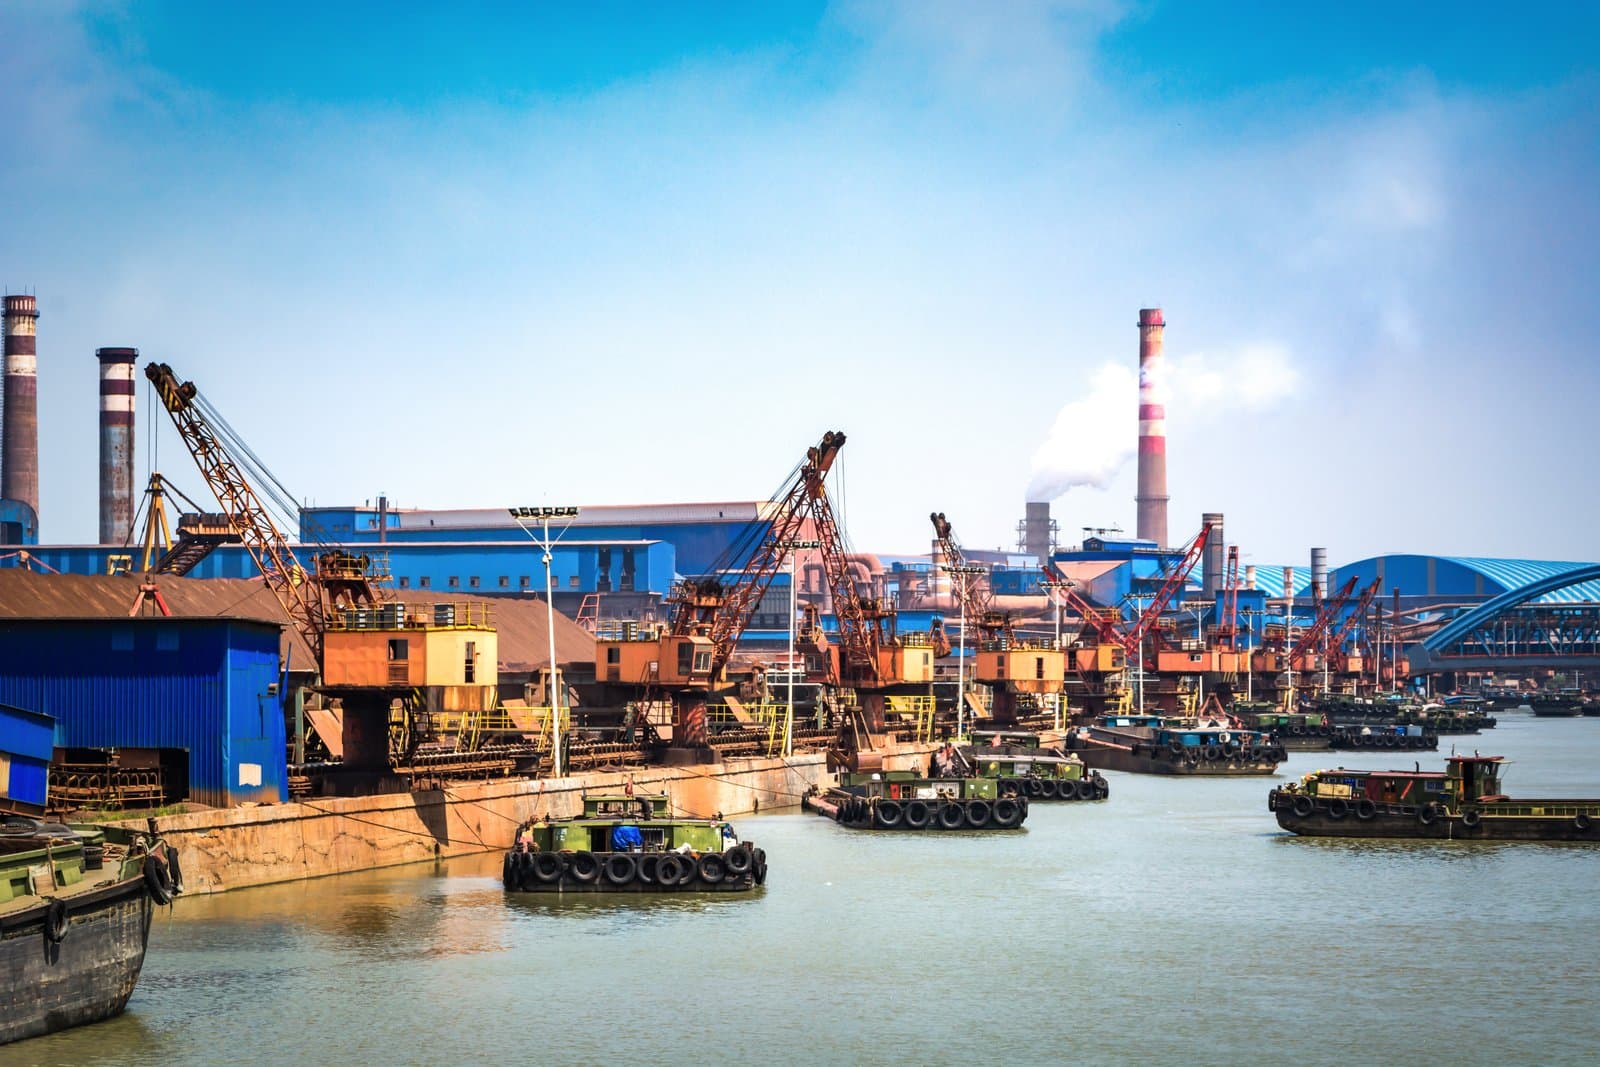 In 2023, analysts predict that China will import a record amount of crude oil due to rising gasoline consumption as more people travel as a result of the removal of COVID-19 regulations and the startup of new refineries.
The issue is cited from Reuters in early 2023. China's crude imports may rise by 500,000 to 1 million barrels per day (bpd) or more this year, reaching as high as 11.8 million bpd, experts from four industry consultancies, including Wood Mackenzie, FGE, Energy Aspects, and S&P Global Commodity Insight, say, this would reverse a decline from the previous two years, and breaking the previous record of 10.8 million bpd set in 2020. The four consultancies predicted that Chinese refineries will boost oil throughput by 850,000 Due to growing local demand and appealing export markets, production is expected to climb to 1.2 million bpd over 2022 levels, or 6% to 9%.
Another positive development for the oil market will be the expectation of robust demand from the largest importer in the world, which will add to the support already provided by the OPEC+ producing group's output cutbacks and western sanctions against Russian shipments.
China has seen an increase in demand for gasoline and jet fuel when COVID limits were removed in December. Sun Jianan, an analyst at Energy Aspects, predicted that gasoline and jet fuel would be the main drivers of the increase in demand for liquid fuels. By the end of 2023, Sun predicted that jet fuel usage would be 90% higher than it was before COVID.
As per FGE analyst Mia Geng and Energy Aspects' Sun, the rebound in China's manufacturing and real estate sectors will take longer to manifest, which will slow down demand growth for diesel, a crucial industrial and transportation fuel, and naphtha, a petrochemical feedstock.
Refiners will be encouraged to increase runs in order to maintain profitable export cargoes and deliver more feedstocks to the petrochemical industry, analysts said, in addition to meeting the growing domestic demand.
Industry sources predict that two new PetroChina-owned refineries, Guangdong Petrochemical and Jiangsu Shenghong Petrochemical, with a combined capacity of 520,000 bpd, would begin functioning commercially in the coming months.
According to a corporate source, a third greenfield refinery, the 400,000 bpd Shandong Yulong Petrochemical facility, may start importing crude towards the end of 2023 in preparation for potential test runs.
Experts did list several reasons to be wary of demand projections despite all the favorable elements. External hindrances, such as a bleak outlook for the world economy, would put stress on China's export industry. The potential for a COVID virus return and the uncertainty surrounding China's fuel export policy were listed as additional risks by analysts.
References:
Aizhu, Chen & Xu, Muyu. 2022. China set for record crude oil imports in 2023, analysts say. Reuters.
Photo by evening_tao via https://www.freepik.com/
Related Insights
BDO Market Shakeup: EU Anti‑Dumping Duties and Chinese Policy Shifts
European anti‑dumping duties on BDO and China’s tightening export rules are reshaping the global supply chain. Traders in spandex, PBT and biodegradable plastics must adapt sourcing strategies now.
10 June 2026 Tradeasia Team
DAP Prices Signal Tight Phosphate Trade
The recent persistence of DAP price strength underscores a tightening phosphate supply chain, heightened global fertilizer demand, and growing procurement risks for agriculture stakeholders. As phosphate trade remains constrained, buyers must reassess sourcing strategies amid volatile market conditions.
22 July 2026 Tradeasia Team
Farm Policy and Fertilizer Cost Relief: Why Long-Term Strategy Must Outlast Short-Term Market Volatility
Government efforts to improve fertilizer affordability continue despite renewed market volatility. Procurement professionals and agricultural businesses should understand how long-term policy initiatives can strengthen supply resilience even when short-term prices remain elevated.
22 July 2026 Tradeasia Team
Japan Country Watch: The 46% Naphtha Import Collapse and the Structural Diversification Outcome
Japan's chemical industry enters H2 2026 after overcoming its most severe naphtha supply disruption in decades. The country's rapid diversification of feedstock sourcing may prove to be the most important long-term outcome of the Hormuz crisis, reshaping procurement strategies well beyond the recovery period.
02 July 2026 Tradeasia Team
Mexico Pemex $5.3 Billion Petrochemical Reinvestment Plan Targets Fertilizer Output Growth Through 2030
Mexico's Pemex has unveiled a $5.3 billion petrochemical and fertilizer reinvestment strategy aimed at dramatically expanding domestic output by 2030. While the plan could reshape regional fertilizer trade over the long term, buyers should not expect immediate relief for tight global nitrogen markets.
22 June 2026 Tradeasia Team
Polyethylene: Quantifying the US Ethane Advantage and Its Practical Limits for Global Buyers
US polyethylene continues to benefit from a structural ethane feedstock advantage, but delivered cost tells a more complex story. This analysis examines freight, regional supply shifts and sourcing strategies that procurement teams should evaluate before placing Q3 and Q4 purchase orders.
02 July 2026 Tradeasia Team
Don't miss out on our updates! Subscribe to our newsletter now
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.