
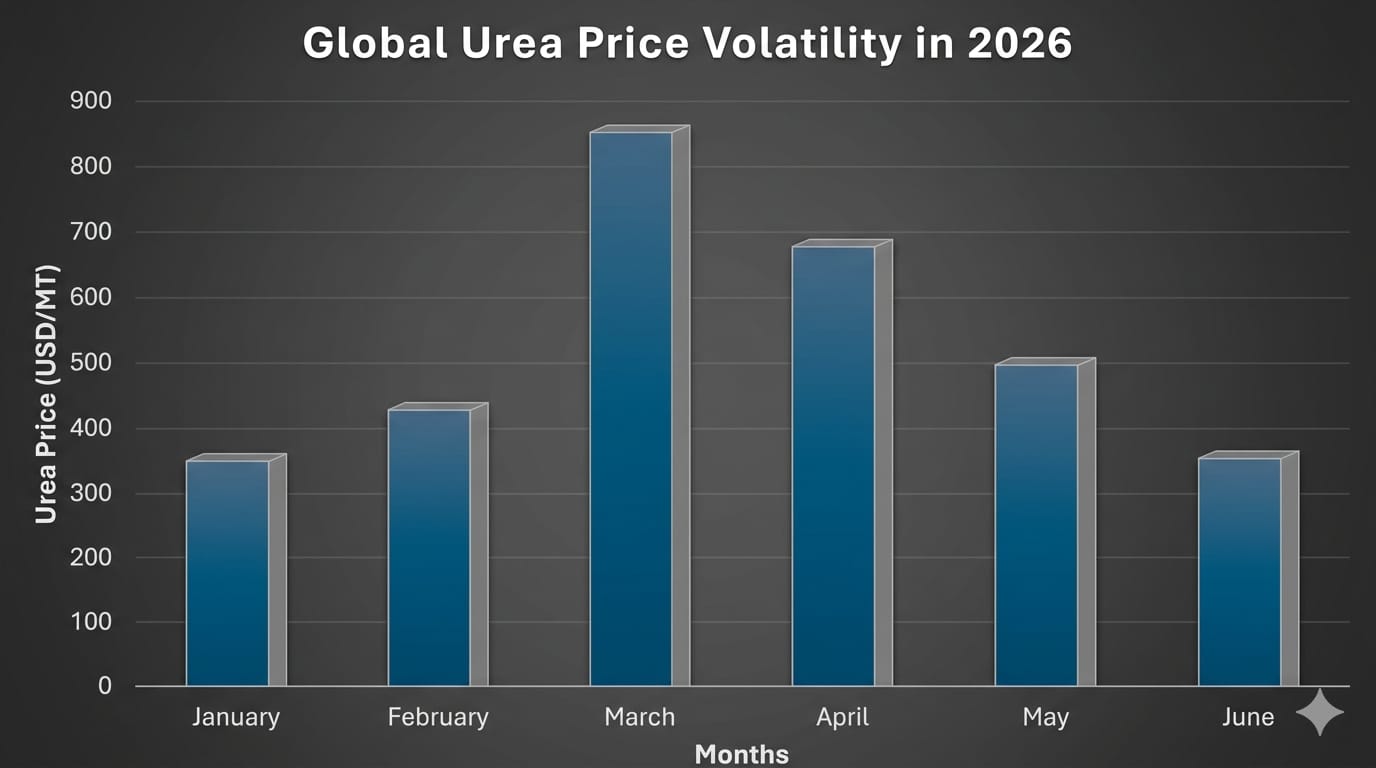
Urea (Granular) - Egypt CAS: 57-13-6
Urea (Granular) - Egypt CAS: 57-13-6
Chinese refining and chemical producers sharply increased price quotations for aromatics and alcohols on July 1, 2026, creating fresh challenges for downstream manufacturers and procurement teams. Buyers should understand what triggered the repricing wave and how it may influence future sourcing strategies.
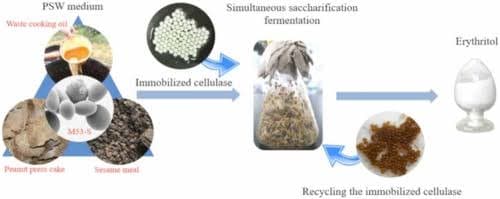
Chinese erythritol producers expanded fermentation capacity through H1 2026 just as GLP-1 driven demand for sugar-free products began accelerating globally. For food and beverage manufacturers, July may be the strongest opportunity to lock competitive H2 erythritol supply before structural demand growth tightens the market later this year.
The vanillin market enters H2 2026 with stable synthetic supply, expanding bio-based production and continued pressure on natural vanilla prices. Procurement teams must balance cost, sustainability, regulatory requirements and product positioning before locking in flavour ingredient contracts.
Nutrien is expected to report exceptionally strong Q2 2026 earnings as sanctions on Russian and Belarusian potash combine with Hormuz supply disruption to tighten global markets. Potash buyers should watch July guidance closely before negotiating H2 contracts.
The return of Gulf MDI exports is reshaping the global polyurethane market after months of limited competition. Adhesive, foam, and polyurethane manufacturers can expect more competitive pricing and stronger supplier negotiations throughout Q3 2026.
Styrene and ABS producers are seeing early signs of supply improvement as benzene availability recovers and feedstock pressure begins to ease. This analysis explores Q3 2026 pricing expectations and procurement considerations for polymer buyers.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.