Africa Chemical Watch: Morocco OCP Capitalises on Phosphate Opportunity, Nigeria and Kenya Update
Introduction
Africa’s chemical landscape in mid-2026 is increasingly defined by divergence rather than uniform growth. The Hormuz disruption has exposed structural differences across the continent’s chemical supply chains, particularly between export-oriented producers and import-dependent economies.
On one side, Morocco is strengthening its position as a global strategic supplier of phosphate-based fertilizers. On the other hand, Nigeria and Kenya are grappling with higher import costs, logistics rerouting, and supply chain instability.
This split is reshaping Africa’s role in the global chemical ecosystem—from a primarily import-reliant region into a more differentiated mix of exporter strength and import vulnerability.
Morocco: Phosphate Powerhouse in a Tight Global Market
At the center of Africa’s chemical export strength is Morocco, led by OCP Group.
Why Morocco matters globally:
Holds the world’s largest phosphate rock reserves
Key supplier of phosphate fertilizers (DAP, MAP, TSP)
Critical player in global food security supply chains
2026 demand dynamics:
Following Hormuz-related disruptions, global buyers—especially in:
Asia
Europe
Latin America
have increased inquiry volumes for non-Gulf phosphate supply.
This has positioned Morocco as a strategic alternative supplier in a tightening fertilizer market.
Dicalcium Phosphate CAS: 7757-93-9
OCP’s Strategic Advantage: From Raw Phosphate to Green Fertilizers
OCP Group is not just benefiting from supply disruptions—it is actively repositioning itself across the fertilizer value chain.
Key strategic pillars:
1. Integrated phosphate production
Mining → processing → fertilizer manufacturing
Strong cost control due to vertical integration
2. Green ammonia integration
Transition toward low-carbon fertilizer production
Alignment with European decarbonization targets
Potential long-term export premium positioning
3. Export diversification
Strong demand from Asia (India, Southeast Asia)
Stable long-term contracts with European buyers
Market implication:
Morocco is evolving from a bulk phosphate exporter into a strategic green fertilizer supplier in the global energy-transition-linked agriculture economy.
Nigeria: Refining Capacity vs Petrochemical Dependence
Nigeria presents a more complex and transitional picture.
Key development:
Dangote Refinery is a central focus of domestic supply transformation.
Strategic importance:
One of Africa’s largest refining projects
Aims to reduce dependence on imported refined products and intermediates
Potential downstream impact on petrochemicals and fuels
Current challenges:
Despite the refinery progress:
Chemical imports remain heavily dependent on Gulf supply chains
Logistics disruptions have increased landed costs
Domestic petrochemical capacity remains limited relative to demand
Market impact:
Nigeria is in a transition phase, where domestic capacity expansion has not yet fully offset import vulnerability.
Kenya: Logistics Stress and Route Realignment
Kenya’s chemical supply chain is heavily import-dependent, making it particularly sensitive to global shipping disruptions.
Key hub:
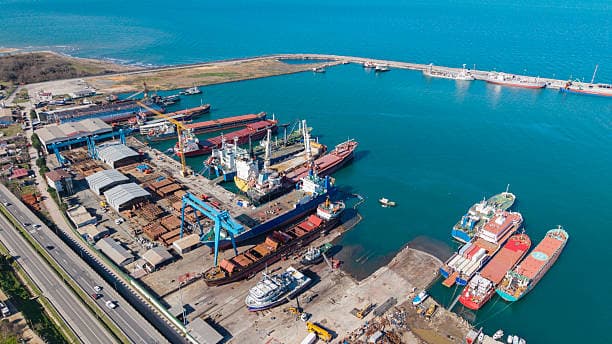
Port of Mombasa
Key developments in 2026:
Increased freight costs due to rerouting via Cape of Good Hope
Longer transit times for chemical imports
Inventory planning challenges for distributors
Sector impacts:
Most affected industries:
Agriculture chemicals (fertilizers, crop protection)
Water treatment chemicals
Industrial cleaning agents
Construction materials additives
Structural challenge:
Kenya’s chemical sector lacks significant upstream production, making it highly exposed to global freight and feedstock volatility.
Africa’s Chemical Divide in 2026
The continent is increasingly split into three categories:
1. Export Leaders (Morocco)
Phosphate dominance
Strategic fertilizer supplier
Increasing green chemistry integration
2. Transition Economies (Nigeria)
Developing refining capacity
Partial import substitution underway
High exposure to external supply chains
3. Import-Dependent Hubs (Kenya and others)
Strong reliance on imported chemicals
High sensitivity to freight disruptions
Logistics-driven price volatility
Impact of Hormuz Disruption on Africa
The Hormuz crisis has amplified existing structural weaknesses:
Key effects:
Higher fertilizer import costs in East and West Africa
Longer supply chains via southern shipping routes
Increased demand for non-Gulf suppliers (notably Morocco)
Inventory shortages in downstream agricultural sectors
However, it has also accelerated interest in:
Regional supply diversification
Local processing investments
Strategic fertilizer sourcing agreements
Fertilizer Security Becomes a Strategic Issue
Africa’s chemical market is increasingly tied to food security.
Why fertilizers matter:
Direct link to agricultural productivity
High dependency on imports in many countries
Sensitive to geopolitical disruptions
Morocco’s role:
Through OCP Group, Africa is emerging as a net contributor to global fertilizer security, even as many African countries remain import dependent.
Strategic Outlook
Africa’s chemical industry is entering a period of structural differentiation:
Key trends:
Export-led strength in Morocco
Infrastructure-led transition in Nigeria
Logistics-constrained import dependency in Kenya
Rising importance of fertilizer security across the continent
The Hormuz disruption has not uniformly harmed Africa—it has redistributed influence within it.
Key Takeaways
OCP Group is strengthening its position as a global phosphate and fertilizer supplier.
Morocco is benefiting from strong global demand for non-Gulf phosphate sources.
Green ammonia integration is positioning Morocco in low-carbon fertilizer markets.
Dangote Refinery represents a key but still-developing step toward Nigeria’s chemical independence.
Kenya’s chemical imports are increasingly impacted by Cape of Good Hope rerouting and higher freight costs.
The Port of Mombasa remains a critical logistics hub for East Africa.
Africa’s chemical sector is splitting into exporters, transition economies, and import-dependent markets.
Fertilizer supply security is becoming a central geopolitical and economic issue.